Category: Business News

  • Say Cheers at 25 – A legacy of distinction, a future of timeless experiences 

    Say Cheers at 25 – A legacy of distinction, a future of timeless experiences 


    Established in 2001 with a clear strategic vision to elevate the wine and spirits experience in Ghana, Say Cheers, has over the years built a brand on expert selection, quality and consistency.

    What began as a personal conviction has evolved into a solid legacy built on taste, trust and an uncompromising commitment to quality. Over, the years, Nana Adwoa Konadu Karikari, the founder and CEO of Say Cheers, has built and sustained a brand with quiet consistency that has redefined industry standards, positioning Say Cheers as a trusted authority in premium beverages over the past two decades.

    Nana Adwoa realized early on that celebrations have been a part of the Ghanaian ethos and was fully convinced that introducing premium beverages would serve a triple purpose of building community, deepening experiences and providing a sustainable source of income. 

    “At the time, a golden opportunity presented itself. Appreciation for premium wines and spirits was gaining momentum. What I saw was a large gap in the market. Wines were being sold, but the market lacked businesses dedicated to delivering a premium wine experience. I believed customers deserved more than a transaction, they deserved an experience. Looking back, I realise that Say Cheers wasn’t born because I just wanted to sell wine, I desired to build something with purpose: a premium experience with wines and spirits.“

    At the core of the its value, Say Cheers believes in not just offering only the best drinks, but ensuring that every lifestyle experience moves us towards a higher level of luxury while creating memories for our clients.

    Say Cheers has grown not only in scale, but in depth, shaped by long-standing relationships with carefully selected vineyards and distilleries across Europe, Australia and South Africa and guided by a deep respect for craftsmanship. The essence of our service is a team which brings a high level of expertise grounded in the art of sommelier, understanding people, their tastes, moments and most importantly what matters to them.

    Say Cheers champions subtle excellence and prioritises consistency and trust over mere scale. Ultimately, it is intention rather than scale that defines our essence. Thus, every experience, every bottle, every drop is a testament to our commitment to excellence. Say Cheers!

  • Financial Inclusion and Strategic Banking Innovation: Reimagining Access in Ghana

    Financial Inclusion and Strategic Banking Innovation: Reimagining Access in Ghana


    In today’s rapidly evolving financial ecosystem, financial inclusion can no longer be measured simply by the number of people who own bank accounts. Across the world, and particularly in emerging economies such as Ghana, the conversation has shifted towards ensuring that individuals and businesses have meaningful access to financial services that improve their lives, support their ambitions, and enable them to participate fully in economic growth.

    This reality calls for a strategic, innovation-driven approach to financial inclusion – one that responds to the complexities of modern life and addresses the unique challenges faced by underserved communities.

    The new face of financial inclusion

    Ghana has made remarkable progress in expanding access to financial services over the past decade. The growth of mobile money, digital payments, and fintech solutions has transformed how millions of people save, transfer money, and conduct business. Yet, despite these gains, a significant portion of the population remains underserved by formal financial systems. Geographic barriers, affordability challenges, varying levels of digital literacy, and trust concerns continue to limit participation, particularly among rural communities, informal sector workers, and small business owners.

    Addressing these challenges requires more than replicating traditional banking models. The future of financial inclusion lies in building intelligent and inclusive systems that meet people where they are. Agent banking networks, mobile-first platforms, digital wallets, artificial intelligence-driven customer solutions, and community-based financial tools all offer opportunities to bridge longstanding gaps in access.

    Ghana’s fintech ecosystem has already demonstrated how technology can help leapfrog traditional infrastructure constraints. Mobile money and USSD-based services, for example, have brought financial services closer to millions of people who may never have visited a bank branch. However, technology alone will not deliver sustainable inclusion. The next phase requires a strategic vision that combines innovation with trust-building, financial education, and a deep understanding of local realities.

    Why innovation must bstrategic

    Innovation, after all, is most effective when it is purposeful. The kind of innovation Ghana needs must be grounded in context and designed around the everyday experiences of the people it seeks to serve. Financial products and services should reflect local economic patterns, cultural behaviours, and the practical challenges individuals and businesses face.

    This means moving beyond one-size-fits-all solutions. A savings product designed for a farmer, for instance, should align with seasonal crop cycles and income patterns. Financing solutions for students could be structured to support educational achievement and long-term financial responsibility. Digital platforms can be designed to simplify access while providing users with greater transparency and control over their finances. These are not distant possibilities. They are practical innovations that can be developed and scaled through collaboration between financial institutions, fintech companies, regulators, educators, and community leaders.

    Equally important is the recognition that access alone does not constitute inclusion. True financial inclusion empowers people to make informed and confident financial decisions. This requires sustained investment in financial literacy, not only through formal education systems but also through community engagement initiatives that help individuals understand and navigate financial products and services.

    Trust remains a critical factor. People are more likely to adopt financial solutions when they understand them, see their value, and believe the institutions behind them have their interests at heart. Building that trust requires transparency, consistent customer engagement, and mechanisms that allow customers to provide feedback and shape the products they use. In many ways, trust remains the invisible currency that underpins successful financial inclusion.

    Beyond access, building financial confidence

    Looking ahead, Ghana’s economic resilience will depend significantly on how effectively it brings more people into the formal financial system. This requires banks to evolve beyond their traditional roles and become centres of innovation that continuously develop solutions for emerging needs. It also requires fintech companies to scale responsibly and inclusively, supported by enabling regulation and strong partnerships across the ecosystem.

    Most importantly, it requires investing in young people – notonly as users of financial services but as creators of the next generation of financial solutions. Their ideas, digital fluency, and entrepreneurial spirit will play a critical role in shaping the future of banking and financial access.

    Financial inclusion should no longer be viewed as an outreach initiative or a social obligation. It is a strategic imperative for national development. By unlocking greater participation in savings, investment, entrepreneurship, and commerce, inclusive finance can help drive productivity and shared prosperity across every sector of the Ghanaian economy.

    Inclusion must be strategic, and strategy must be inclusive. That is how Ghana can build a financial system that leaves no one behind.

    Joseph Cobbinah, Complaints Management & Information Analyst, Client Experience, Personal and Private Banking, Stanbic Bank Ghana

  • Beyond Borders: How CIPS and PAPSS Can Power Ghana’s Next Chapter of Trade

    Beyond Borders: How CIPS and PAPSS Can Power Ghana’s Next Chapter of Trade


    Every exporter or importer who has waited for days for a payment to clear or watched a shipment’s margin erode to a currency conversion, understands the truth that policy documents rarely capture: trade doesn’t fail at the border. 

    It fails in the payment. Goods can move freely across a continent, but if the money behind them takes a week and three intermediaries to arrive, that freedom means little. 

    This is the quiet problem Ghana’s next phase of trade growth depends on solving, and it’s why two systems with unglamorous acronyms, CIPS and PAPSS, deserve more attention in boardrooms than they currently get.

    The Cost of Doing Business Across Borders

    For years, Ghanaian businesses trading internationally have leaned on correspondent banking networks, chains of intermediary banks that route a payment from one currency system to another, usually settling in US dollars regardless of where the goods actually originate. Each link in that chain adds cost, time, and uncertainty. 

    Payment can take days to clear, exchange rates can move against a business mid-transaction, and visibility into where funds actually sit is often poor. For large corporates with treasury teams, this is manageable friction. 

    For small and medium enterprises, which make up the backbone of Ghana’s export base but rarely have the resources to hedge currency risk or absorb delayed settlement, it can be the difference between winning a contract and losing it to a competitor with faster, cheaper payment rails.

    Intra-African trade has suffered the same fate. Even between neighboring countries, payments have often had to be routedthrough currency conversions and external correspondent banks before reaching their destination, adding cost to transactions that should, in principle, be simple.

    Two Systems, Different Jobs

    PAPSS, the Pan-African Payment and Settlement System, and CIPS, China’s Cross-Border Interbank Payment System, solve different pieces of this puzzle. 

    PAPSS allows businesses to settle payments directly in local currencies across participating African markets, cutting out the need for multiple conversions and reducing reliance on correspondent banks altogether. That translates into lower costs, faster settlement, and far greater certainty for businesses trading within the continent. 

    CIPS operates on a different corridor entirely, giving Ghanaian businesses a more direct channel for Renminbi denominated transactions with China, Ghana’s largest trading partner. Fewer intermediary steps mean fewer points of failure and faster, cheaper settlement when trading with Chinese counterparts.

    Used together, the two systems don’t compete; they complement. One strengthens Ghana’s position within Africa, the other strengthens its connection to Asia and together they give Ghanaian businesses a more resilient, diversified way to move money that matches how they trade.

    Turning Policy into Practice

    The African Continental Free Trade Area promises a single market of over a billion people, but a single market only works if payments move as freely as goods do. PAPSS is the infrastructure that makes that promise practical rather than aspirational and its public launch in Accra, alongside Ghana’s role as host of the AfCFTA Secretariat, places the country at the center of that shift rather than on its periphery.

    The businesses best positioned to feel this shift are Ghana’s SMEs. For smaller importers and exporters, payment costs eat up a disproportionate share of every transaction, and slow settlement can tie up working capital they can’t afford to lose. 

    Faster, cheaper, more transparent payment rails give these businesses room to compete in markets that were previously too costly to enter, whether that’s a trader sourcing raw materials for manufacturing, an agribusiness reaching new export markets, a mining company settling with international partners, or a digital services firm delivering across borders. 

    The sectors that benefit most are, unsurprisingly, the ones most exposed to cross-border commerce in the first place.

    What Still Needs to Change

    None of this happens automatically. Technology can build the rails, but businesses still need to know how to use them. That means boards and management teams treating payment infrastructure as a strategic lever for growth rather than a back-office banking function, and it means stronger treasury capabilities and digital literacy across the business community. 

    Regulators, banks, fintechs, and trade bodies all have a role to play in closing that gap, and banks in particular carry real responsibility here: educating clients, supporting onboarding, structuring trade finance, and helping businesses navigate the compliance and foreign exchange requirements that come with any new payment channel. 

    Interoperability between banking systems and regional networks, alongside continued vigilance on cybersecurity and anti-money laundering compliance, will determine how smoothly this infrastructure scales.

    Ghana’s Next Chapter

    Ghana already sits in a strategically valuable position: home to the AfCFTA Secretariat, an early adopter of PAPSS, and one of the African markets live on the CIPS rail. 

    If the country continues building out this payment infrastructure with the same intent it has shown so far, the destination is a Ghana that trades more competitively across Africa, settles more efficiently with Asia, and attracts the kind of regional treasury and headquarters functions that come with a genuine financial hub status. 

    Trade agreements open the doors. Payment systems are what let businesses actually walk through them. Ghana has an opportunity most countries on the continent don’t yet have, and the work now is making sure its businesses are ready to use it.

    Kate Agamah, Head, Transaction Banking, Corporate and Investment Banking, Stanbic Bank Ghana.
  • Maison Yusif Fragrance Makes History at FragCon 2026, Wins Major Award and Sells Out in Houston

    Maison Yusif Fragrance Makes History at FragCon 2026, Wins Major Award and Sells Out in Houston

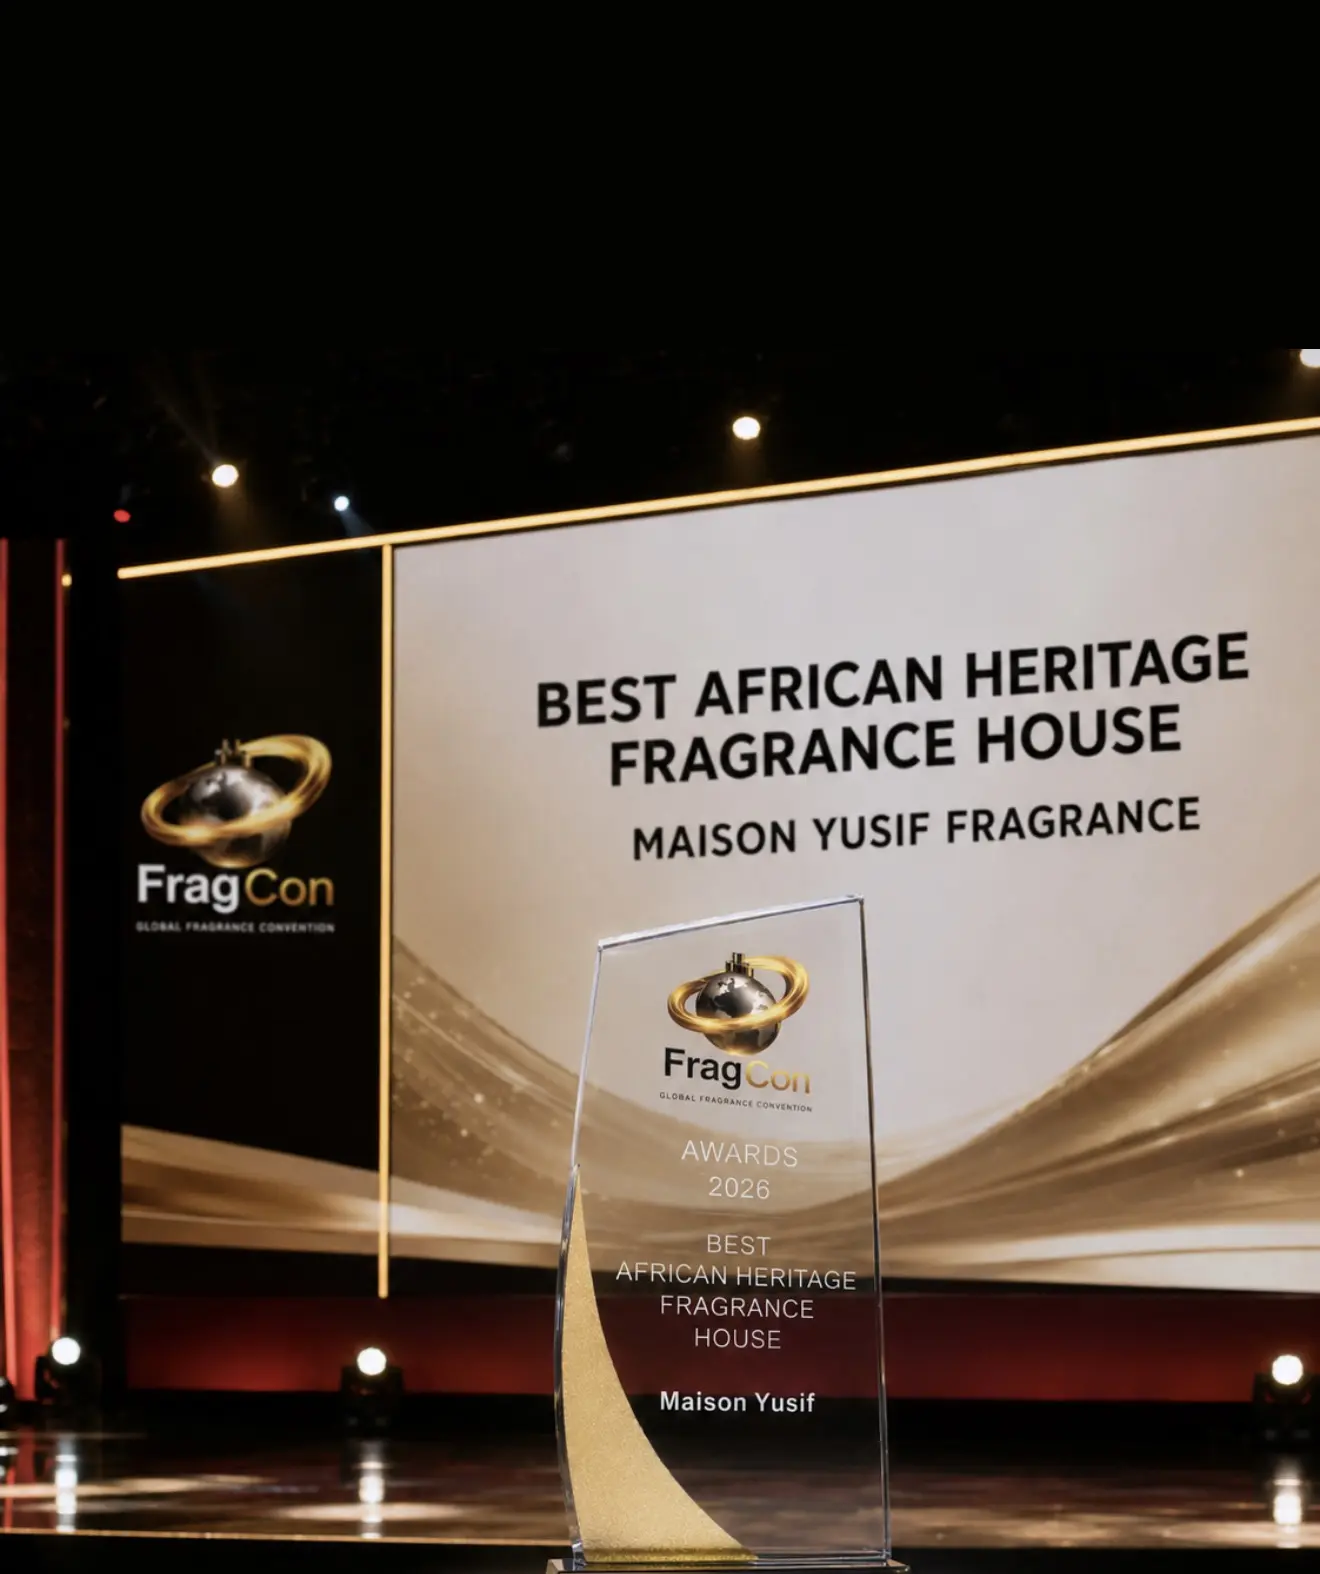
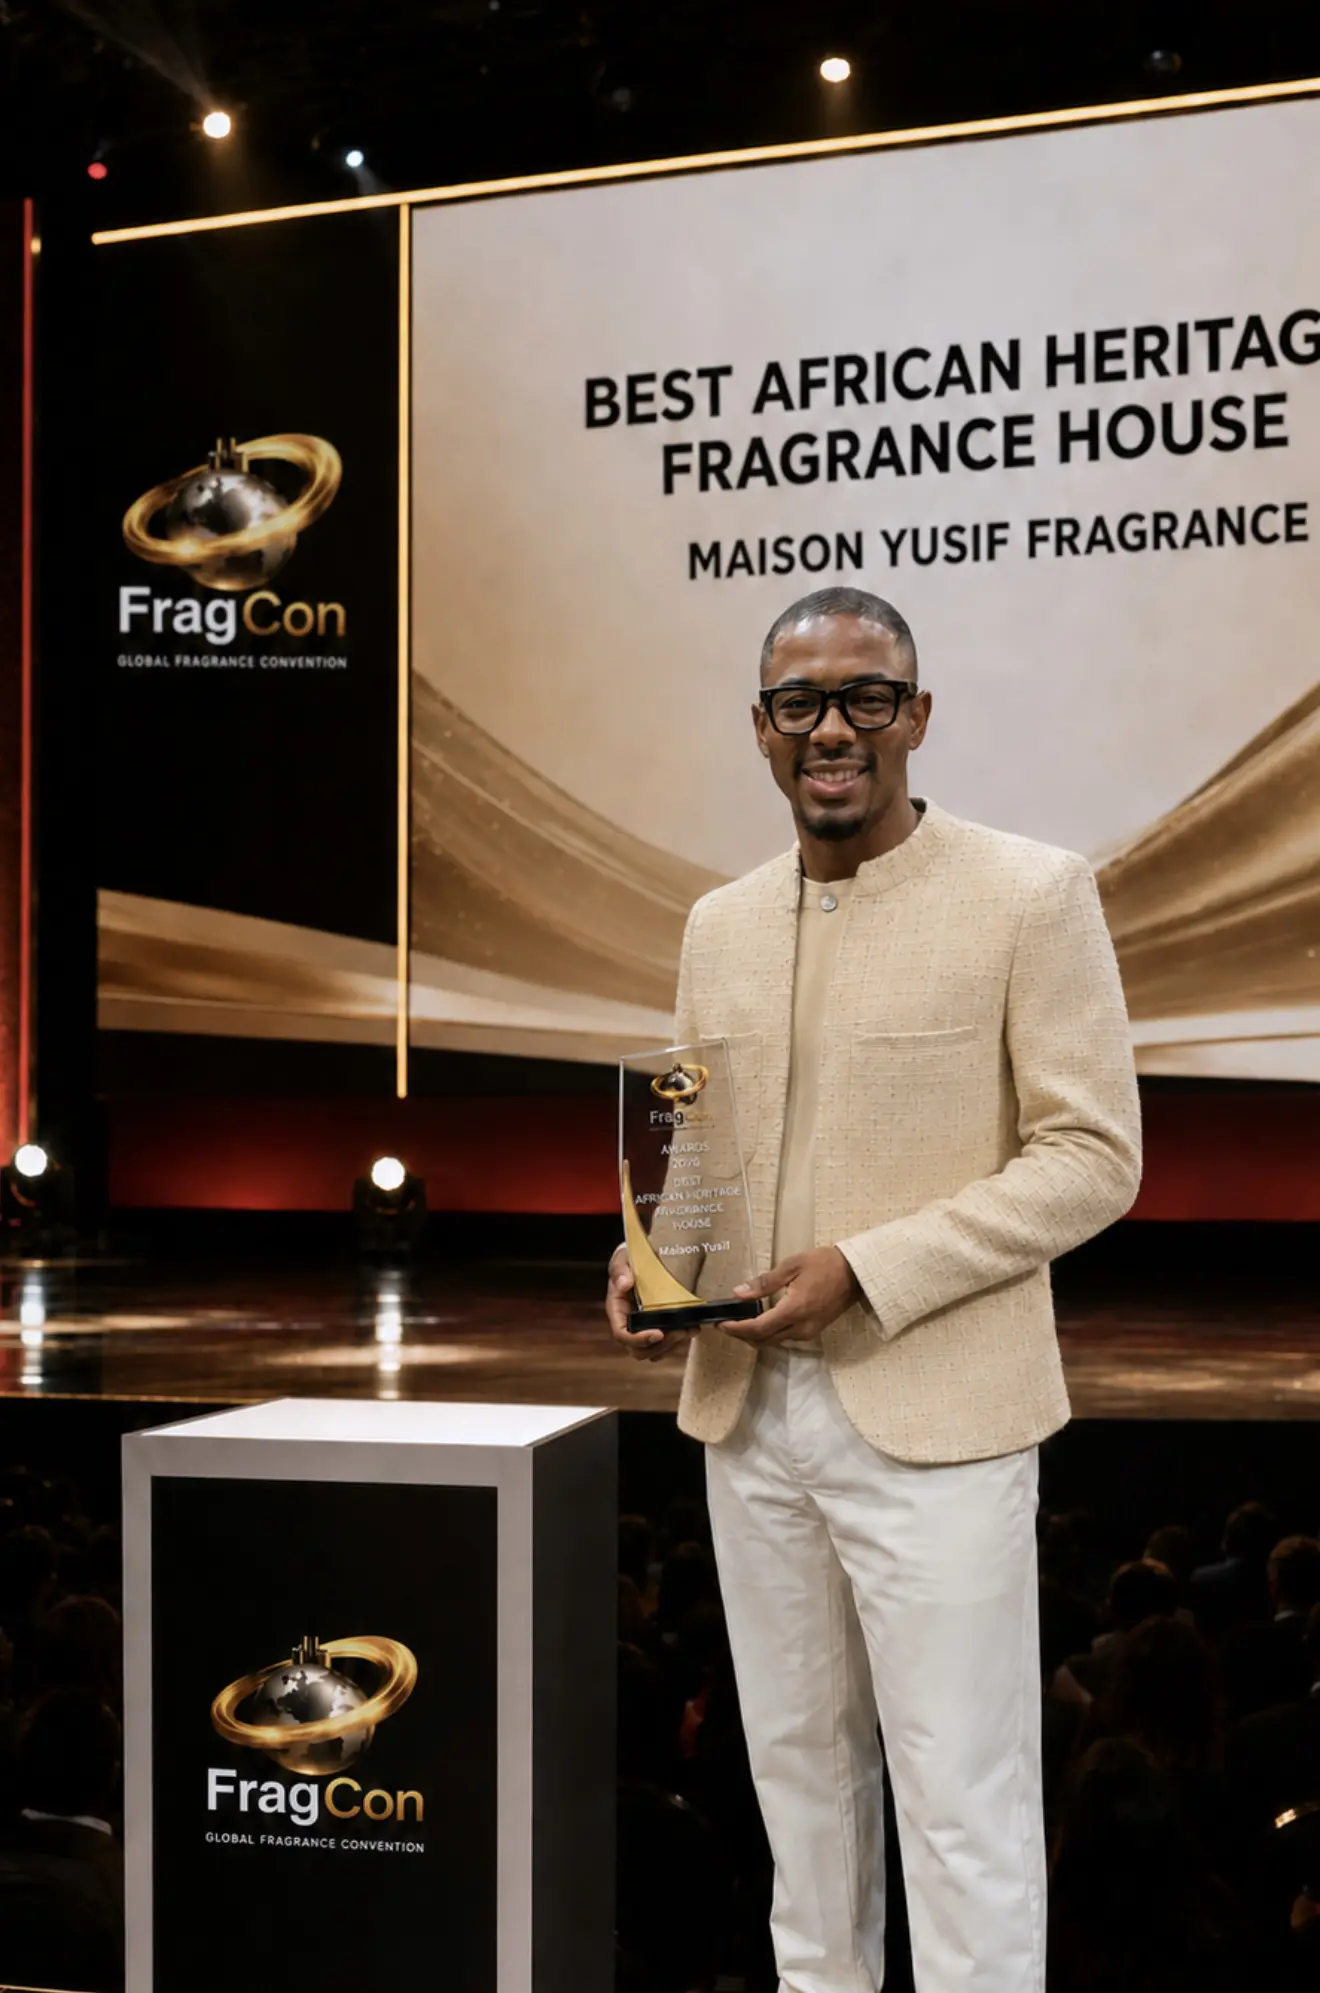
    Houston, Texas — Ghanaian luxury fragrance house Maison Yusif Fragrance has reached another significant international milestone after winning Best African Heritage Fragrance House at the FragCon Awards 2026 in Houston, Texas.

    The recognition marked a historic achievement for the brand, which became the first Ghanaian fragrance house to exhibit at FragCon and the first from Ghana to receive the prestigious award.

    Maison Yusif’s participation was equally successful commercially. The fragrance house completely sold out its collection before the convention’s second day, demonstrating the growing international demand for its Ghana-made fragrances.

    Founded in Accra by certified perfumer Yusif Jnr Meizongo, Maison Yusif Fragrance has built its identity around African heritage, artistic perfumery and world-class craftsmanship. The brand transforms African stories, ingredients and experiences into distinctive luxury fragrances capable of competing on the global stage.

    “This recognition belongs not only to Maison Yusif, but also to Ghana and every African creative working to show the world what our continent can produce,” said Meizongo. “We arrived at FragCon carrying Ghana’s name, our heritage and our vision. To sell out and receive this award made the experience even more meaningful.”

    The FragCon achievement adds to Maison Yusif’s growing record of international recognition. The company has expanded beyond Ghana, established retail presence in international markets and represented African perfumery at prominent fragrance events around the world.

    Through these achievements, Maison Yusif is helping to place Ghana firmly on the global fragrance map. In an industry historically dominated by European and Middle Eastern houses, the company is proving that an African fragrance brand can create original, luxurious and internationally celebrated perfumes while remaining deeply connected to its heritage.

    Maison Yusif has emerged as one of Ghana and Africa’s leading niche fragrance houses, earning recognition for its creativity, quality and contribution to the development of African perfumery. Its success at FragCon further strengthens its position as a standard-bearer for Ghanaian and African luxury fragrance.

    The brand’s historic appearance, complete sellout and award victory delivered a powerful message: African perfumery is no longer waiting to be discovered—it has arrived.

    For Maison Yusif Fragrance, this moment represents more than another trophy. It is evidence that a dream created in Ghana can travel across borders, command global attention and inspire a new generation of African perfumers.

    Maison Yusif Fragrance represented Ghana, sold out and made history—once again proving that the future of African luxury can be proudly created in Africa.

  • Ghana’s New Wealth Window

    Ghana’s New Wealth Window

    Ghana’s 2026 Mid-Year Fiscal Policy Review, presented to Parliament on 23 July under the theme “Resetting for Growth, Jobs and Economic Transformation,” reads like routine housekeeping – no supplementary budget, spending held within the approved ceiling. Read properly, it is something bigger: a signal to every bank, insurer, pension fund, business and household that the rules of the game have changed.

    Government chose to redirect existing resources toward infrastructure, transport, flood control, energy security and debt management rather than ask for more. That choice ripples outward. Fiscal discipline shapes inflation, interest rates, the exchange rate, and market confidence – which determines whether banks can profit, businesses can borrow, investors can grow portfolios, and households can finally afford a home, a pension, or productive land. Capturing this moment demands a shift in habits: banks weaning off government paper toward real lending, investors chasing actual returns instead of headline rates, households converting income into assets rather than consumption.

    The Numbers Behind the Reset

    Government has reaffirmed its 2026 targets; growth of at least 4.8 percent, inflation at 8 percent, a primary surplus of 1.5 percent of GDP, and is already ahead of schedule. First-quarter GDP growth hit 6.4 percent, reserves covered five months of imports by June, and inflation fell from 13.7 percent a year earlier to roughly 5.3 percent. Public debt has dropped from 61.8 percent of GDP at the end of 2024 to about 45 percent by mid-2026, with Ghana’s debt distress rating upgraded from high to moderate. None of this is abstract: investment flourishes only where inflation is tamed, debt is sustainable, and the future value of money is something people can plan around.

    A Different Game for Financial Institutions

    The most immediate shock will hit interest rates. The Monetary Policy Rate has fallen from 27 percent in January 2025 to 14 percent, while the 91-day Treasury Bill rate has collapsed from 11.09 to 5.73 percent, and bonds that traded near 20 percent a year ago now sit between 11 and 12.6 percent.

    For banks, pension funds and insurers, this cut both ways. The comfortable years of earning strong, low-risk returns simply by parking money in government paper are narrowing, but cheaper yields should push institutions toward real lending — mortgages, business loans, equipment and vehicle finance, working capital — where the income potential is far greater. The winners will gather deposits cheaply, price loans sensibly, keep bad loans under control, and build products beyond the ordinary savings account. Government has already shored up the sector, recapitalizing five state and quasi-state banks and issuing a GH¢5 billion recapitalization bond to the Bank of Ghana, capital that should mean more lending capacity, provided governance keeps pace.

    That same rate shift should force product innovation. As Treasury Bill returns fade, savers will want mutual funds, bond and equity funds, mortgage and education savings plans, and managed portfolios  and these shouldn’t remain the preserve of the wealthy. A teacher, nurse or trader deserves the same access, backed by honest disclosure on charges and expected returns. Trust and education, not product design alone, will decide how far wealth management spreads.

    Business, Investment, and the Household Balance Sheet

    Businesses stand to gain from cheaper financing and a lighter tax load several levies including the Electronic Transfer Levy and COVID-19 Health Recovery Levy have been scrapped, effective VAT has dropped from 21.9 to 20 percent, and the VAT registration threshold has risen to GH¢750,000, freeing up working capital, particularly for SMEs, to restock, hire, modernize or digitize. With 87 infrastructure projects underway across all sixteen regions, banks, insurers, contractors and suppliers all stand in line for spillover benefit. The trade-off is tighter enforcement: Ghana loses an estimated 60 percent of potential VAT revenue to non-compliance, and electronic invoicing and digital customs monitoring will make it much harder to hide transactions.

    Investors, meanwhile, need to unlearn the habit of chasing headline yield. A 10 percent return against 5 percent inflation preserves wealth better than a 25 percent return against 30 percent inflation ever did. Diversification across cash, bonds, equities, pension products and property becomes essential, alongside real due diligence rather than blind faith in a promising sector. The Sinking Fund’s climb toward GH¢30 billion by year-end is itself a quiet vote of confidence in Ghana’s ability to meet its obligations.

    For households, falling inflation means income stretches further, while cheaper lending could widen access to mortgages, education finance and business credit. The task now is discipline: build an emergency reserve, clear expensive debt, insure against shocks, contribute to a pension, and invest through regulated institutions rather than unlicensed schemes. The real danger is treating cheap credit as spending money – aloan for a business or an education builds value; a loan for consumption becomes tomorrow’s burden.

    The Opportunity Won’t Convert Itself

    Every actor faces the same test. Institutions will see passive income from government paper shrink but can gain from credit demand if they lend responsibly. Businesses get room to expand if they invest productively rather than merely bank the tax relief. Investors need discipline over habit, and households need to turn improving conditions into savings rather than short-term comfort. None of it happens automatically, it requires government to hold the line, banks to pass on lower rates honestly, businesses to invest, investors to do their homework, and households to convert income into assets.