
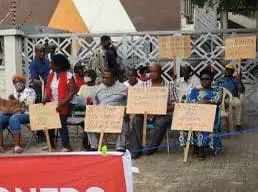

A group of pensioner Eurobond holders in Ghana is crying foul over the government’s recent $13 billion debt restructuring deal, demanding exemption from the agreement’s harsh terms. The retirees are concerned that being included in the debt exchange without a hearing will exacerbate their vulnerability and lead to a heavy financial burden.
The group had submitted multiple appeals to the Ministry of Finance for an exclusion, but their grievances were ignored. They are now urging the government to reconsider and exempt them from the deal’s harsh terms, which include a 37 percent haircut, reduced interest rates, and extended maturity dates of up to 10 years.
The pensioners are seeking meaningful dialogue with the government to explore alternative solutions that safeguard their financial well-being. They argue that the current agreement will only worsen their economic situation, making it difficult for them to survive on their fixed incomes.
Ghana’s debt restructuring deal was reached in June 2024, after months of negotiations with international creditors. The agreement involves a nominal 37 percent haircut on investments, with bondholders having the option to choose between two instruments: one offering an initial 5 percent interest rate and the other a 1.5 percent interest rate.
While the government hailed the deal as a major breakthrough, the pensioner Eurobond holders say it fails to consider their unique circumstances. They are calling on the government to revisit the agreement and provide relief to vulnerable groups like themselves.
Ruth Abla ADJORLOLO